Pay Cost of Living: A UK Guide to Managing Rising Household Costs
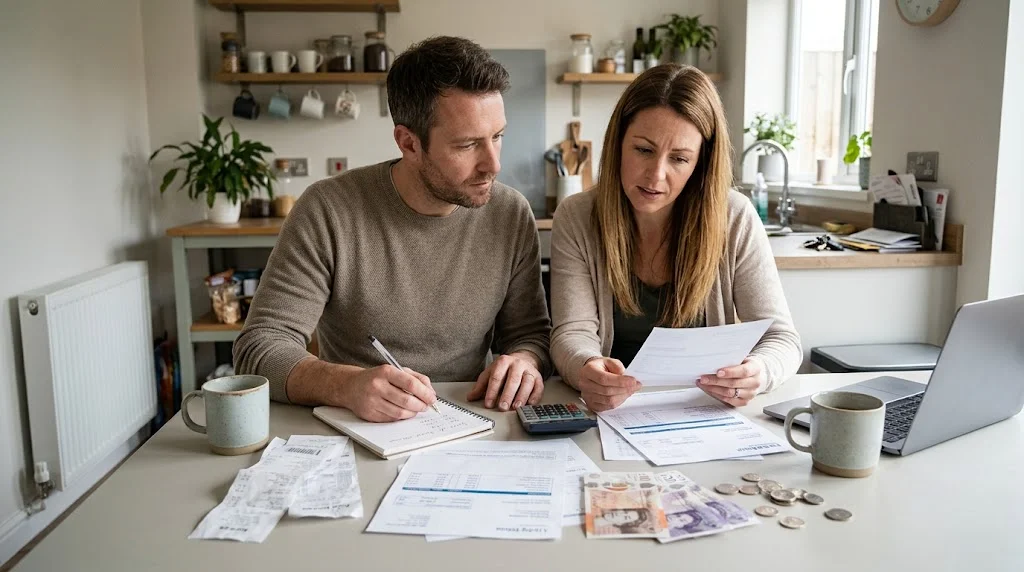
The cost of living covers everyday expenses: housing, energy, food, transport, internet, and smaller recurring charges. Pay cost of living simply means covering these essentials with your monthly income without falling behind.
That explains why gradual price rises feel different from a single big expense. You can plan for a one-off bill. A steady price hike is sneaky. The same groceries, commute, and heating quietly eat up more of your paycheck. Consequently, the month ends tighter than before.
Economists call this general rise in prices inflation. In the UK, the Office for National Statistics (ONS) tracks this through official measures like CPI and CPIH. Its monthly consumer price inflation bulletin provides the most accurate updates. The core idea is simple: as prices climb, each pound buys less.
How rising costs squeeze your household budget
Price hikes hit every household differently. The exact pressure depends on where most of your money goes.
Housing and energy form your biggest fixed costs. They are also the hardest bills to reduce quickly. You must pay cost of living, mortgage, council tax, and power bills first. When these jump, they shrink your remaining cash immediately.
Food comes next. While groceries are essential, daily shopping habits give you room to trim the total.
Transport is the third major pressure point, though people often overlook it. Fuel prices, train fares, insurance, and repairs fluctuate on different cycles. Drivers notice rising fuel costs instantly. Meanwhile, train and bus commuters feel annual fare hikes.
To manage these pressures, you first need an honest view of your cash flow.
Track one month of spending honestly
Budget plans often collapse because they set unrealistic goals upfront. Before cutting back, simply record every penny you spend for four weeks.
Group your expenses into clear categories:
-
Housing and energy
-
Groceries
-
Commuting and transport
-
Phone and broadband
-
Subscriptions
-
Miscellaneous spending
Your mobile banking app makes tracking simple, but a notebook works just as well.
At the end of the month, divide your spending into three clear buckets:
-
Essentials: Costs you cannot skip, such as rent, heating, basic food, travel to work, and minimum debt payments.
-
Flexible costs: Important expenses you can trim, such as grocery brands, takeaway meals, or mobile packages.
-
Discretionary extras: Forgotten subscriptions, impulse buys, and daily habits that bring little joy.
Most people discover a surprise in that third bucket. You will likely find small, regular charges that slipped your radar. Do not feel guilty about them. These leaks are actually the easiest costs to stop because cutting them rarely hurts.
Prioritise essentials, then work outwards
Once you see your real spending habits, prioritize your decisions clearly.
Pay your essentials first, in full and on time. Skipping rent, power, or debt payments triggers costly fees, credit damage, and severe stress.
Next, target your largest flexible costs rather than tiny splurges. You save far more by trimming a large grocery bill by 10% than by skipping one coffee.
Apply these practical food-saving steps:
-
Plan weekly meals around ingredients already in your pantry.
-
Always shop with a strict grocery list.
-
Compare unit prices (cost per 100g) instead of pack prices.
-
Throw away less food. Wasted food is wasted cash.
Take the same practical approach with home energy. Focus on heating habits rather than obsessing over an LED bulb. Turn off radiators in empty rooms, block cold draughts, and switch off idling electronics. If you switch energy tariffs, review the standing charges along with the headline unit rate.
For travel, look for simple changes. Walk or cycle for short journeys, share car rides, or group your errands together. Only choose alternatives that fit your daily schedule, health, and personal safety.
Audit recurring subscriptions and memberships
Subscriptions easily drain your bank account because companies design them to be forgotten. Streaming platforms, apps, gym passes, and delivery memberships add up quickly. Together, they can easily equal a utility bill.
List every recurring payment, including annual direct debits. Ask yourself two questions for each:
-
Did I actually use this service in the last 30 days?
-
Would my life suffer if I stopped it this week?
Keep the services you love. A budget that cuts out every comfort never lasts. Cancel, pause, or downgrade the rest. Revisit this list every three months to catch creep.
Build a small emergency cushion
An emergency buffer protects you from surprises like broken boilers, car repairs, or sudden bills. It keeps an unexpected expense from turning into high-interest debt. Taking out loans during an emergency usually costs far more than the repair itself.
Start with an amount you can easily afford, even £10 or £20 a week. Set up an automatic transfer on pay cost of living. Waiting until month-end rarely works, as extra cash usually vanishes. Move this money into a separate savings account so you resist dipping into it.
A cash cushion gives you breathing room. With a buffer in place, you avoid desperate, high-interest borrowing.
What to do when your income falls short
Sometimes an honest budget reveals a painful reality: trimming extras still leaves you unable to afford essentials. That is not a personal failure, and strict budgeting alone will not solve it. You need to seek help early, before arrears pile up.
In the UK, charities provide free, confidential debt advice. Energy providers and housing associations also run hardship programs for struggling households. Call your providers immediately if you cannot pay. Staying silent always makes the situation worse.
Check whether you qualify for unclaimed state support or local grants. Many families miss out on aid simply because they never applied.
Avoid borrowing to pay cost of living. Adding loan repayments to an unbalanced budget deepens the hole. High-cost, short-term credit is particularly dangerous. Always consult an independent debt adviser before taking on new debt.
Sensible habits that last
Managing living costs does not require drastic misery. It simply takes clear visibility, smart priorities, and consistent daily habits.
Know where your cash goes, protect your essentials, tackle your biggest flexible expenses, and trim sneaky subscriptions. Build whatever buffer you can afford. Review your budget monthly at first, and then quarterly as your costs and income shift.
FAQs
What does “pay cost of living” mean?
It means earning enough income to cover your basic daily needs—such as rent, heating, groceries, and travel—month after month without falling into arrears.
What is the best first step when living costs spike?
Track every penny you spend for four weeks. Sorting your expenses into essentials, flexible costs, and extras shows you exactly where to make quick savings.
How can I lower food and energy bills without misery?
Tackle waste directly. Cook with ingredients you already own, shop with a list, heat only occupied rooms, and seal home draughts.
Should I save money if my budget is extremely tight?
Yes. Even saving a few pounds each payday builds a small barrier against sudden emergencies and costly loans.
What should I do if my earnings cannot cover basic bills?
Contact your suppliers right away to arrange manageable payment terms. Then, speak with a free, independent debt adviser and check for unclaimed support.
Where can I check current UK inflation rates?
The Office for National Statistics (ONS) publishes the official CPI and CPIH figures every month in its consumer price inflation bulletin.

Post Comment